Trucking remains essential to the U.S. economy. According to the Logistics Manager Index, trucks move roughly 72.7% of the nation’s freight by weight. In 2025, they transported 11.26 billion tons of freight and generated $936.4 billion in revenue. Small carriers make up most of the sector: 91.1% operate 10 or fewer trucks.
For risk teams, the scale of trucking matters—but so does the gap between strong freight demand and rising pressure on carriers’ finances. Current data show a sector with opportunity, tighter capacity and increasing credit activity, alongside high operating costs and signs of elevated credit risk. The key question is how well individual businesses can turn demand into sustainable cash flow.
Watch the Commercial Pulse Update
Demand is firm, but industry structure is changing
Logistics activity has remained in expansion for nearly three years. In September, transportation capacity was still contracting for a tenth consecutive month, while utilization remained in expansion. The load-to-truck ratio reached its highest point in several years, suggesting that available freight is high relative to available trucks.
For carriers that can keep vehicles productive, tight capacity may support pricing and utilization. But those conditions do not automatically translate into stronger margins. Higher rates can be offset by fuel, maintenance, insurance and equipment costs—and those expenses can vary considerably from one business to another.
The sector’s structure is shifting, too. Medium- and heavy-duty vehicles in operation were 4.8% higher in the second quarter of 2026 than a year earlier, even as the number of trucking businesses has declined since 2023. Employment has also fallen steadily since 2023, following a post-pandemic surge. Together, these trends point to consolidation and a more complex operating landscape: fleet counts, business counts and employment may tell different parts of the story.
Costs are a central source of risk
The cost of moving goods continues to climb. In September, the Producer Price Index for truck transportation reached a record high. The Logistics Managers’ Index transportation prices measure rose 2.7 points to 92.7, remaining near historic highs. Diesel prices were roughly 73% above their year-earlier level.
For risk leaders, persistent cost pressure matters because it can affect liquidity before it is fully reflected in longer-term performance measures. A carrier may have a full order book and still face working-capital strain if fuel and other operating costs rise faster than it can adjust pricing or collect from customers.
This makes it useful to view demand and cost indicators together. A high load-to-truck ratio can be supportive, but it should be read alongside operating expenses, capacity, and the financial flexibility available to each carrier. The sector-wide picture provides context; it cannot establish whether a particular business can absorb the next cost increase.
Credit appetite can signal confidence and need
Experian commercial credit data show that trucking businesses have generally sought credit more often than businesses in other industries. Commercial inquiries per business have increased over the past two years, and new commercial account openings have trended upward since mid-2024. Average loan amounts have increased over the past year, while average loan sizes across industries have moved closer together since 2024.
Credit activity alone does not tell a CRO whether a business is borrowing to support growth or to bridge a cash-flow gap. In a high-cost environment, the same increase in applications can reflect both opportunity and funding need. It is a signal to interpret with other information about the business and its ability to manage obligations.
Commercial card patterns add another layer. Trucking businesses tend to open more new commercial card accounts but receive lower credit lines than businesses in many other sectors. Their average balances are lower, yet their utilization is consistently higher. Lower balances can obscure how little unused capacity a business may have. For risk teams, utilization relative to available credit may therefore be more revealing than balance size alone.
Watch for deterioration, not just growth
Trucking businesses tend to have higher delinquency rates than businesses in other sectors, and average commercial risk scores indicate greater risk. These aggregate patterns deserve attention, especially alongside elevated costs and high card utilization. They do not mean every trucking borrower is deteriorating; they identify areas where portfolio monitoring may be useful.
A CRO can use sector trends to sharpen questions at the borrower level: Are operating costs rising faster than revenue? Is available credit shrinking as utilization increases? Are payment patterns changing? Can the business maintain liquidity if freight volumes, pricing or fuel costs shift? The answers will differ across carriers, depending on their operations and financial position.
A risk picture with both opportunity and pressure
The trucking outlook is constructive but uneven. Strong freight demand and tighter capacity may benefit disciplined carriers. At the same time, record transportation costs, industry consolidation and elevated credit-risk indicators create pressure that may be harder for thinner-margin businesses to absorb.
For risk leaders, the most useful takeaway is to avoid treating a strong demand signal as a complete picture of credit health. Pair freight and capacity trends with cost pressure, credit utilization and payment performance, then assess what those patterns mean for each business. In trucking, opportunity is real—but so is the need to understand which carriers have the financial resilience to capture it.
Learn more
- ✔ Visit our Commercial Insights Hub for in-depth reports and expert analysis.
- ✔ Subscribe to our YouTube channel for regular updates on small business trends.
- ✔ Connect with your Experian account team to explore how data-driven insights can help your business grow.
Related Posts
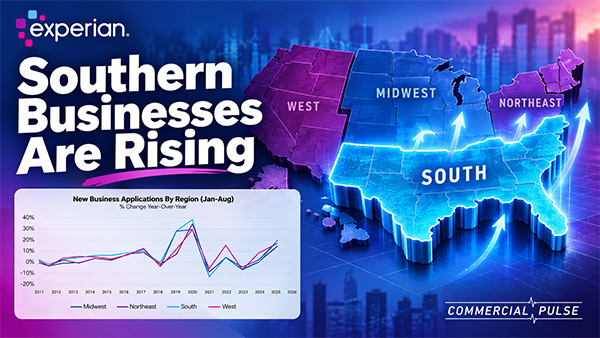
Small business formation remains one of the more notable trends in the U.S. economy. In August 532,000 new businesses launched across the country. While that was down from July, it remained well above historical averages. Since July 2020, an average of 455,000 new businesses have opened each month—56% higher than the pre-pandemic monthly average in 2018 and 2019. But the national numbers only tell part of the story. Watch The Commercial Pulse Update Experian’s latest Commercial Pulse report analysis examines where this growth is occurring and what it means for the commercial credit market. The data show that the South has emerged as an important center of small-business growth. And the businesses driving that expansion tend to have a different profile from their counterparts in other regions. For commercial lenders, understanding those differences can provide valuable context when evaluating new opportunities, credit demand and portfolio risk. Business growth is shifting geographically New business formation has increased across all U.S. regions, but the pace has not been uniform. Prior to 2018, regional differences in growth were relatively modest. During the pandemic years of 2020 and 2021, the South led the country in new business application growth. Since 2022, the West has posted the strongest growth, while the South continues to account for the greatest volume of new business openings. One factor providing context for that growth is population. The population of the South has grown more than 7% since 2019. Since 2020 alone, the region has added more than 3.6 million residents, outpacing every other U.S. region. Meanwhile, populations in other parts of the country declined between 2020 and 2022 before beginning to recover. Business formation and population movement do not necessarily have a simple cause-and-effect relationship. But their parallel growth highlights how the geographic makeup of both consumers and businesses has been changing. Credit-active businesses are growing even faster in the South The shift becomes even clearer when looking at businesses using commercial credit. Experian data shows the number of credit-active businesses in the United States has increased 55% since 2018. Every region participated in that expansion, but the South experienced the greatest growth at 70%, followed by the North at 52%, West at 50% and Midwest at 36%. The South now represents approximately 39% of U.S. credit-active businesses. It also accounted for more than 40% of newly opened commercial accounts in 2026, compared with 37% in 2019. For commercial credit organizations, that means the South represents not just a growing population of businesses, but an increasingly significant share of businesses participating in the commercial credit ecosystem. Southern businesses tend to be smaller and younger The composition of this growth is just as important as its scale. Credit-active businesses in the South and West tend to skew smaller and younger than those in the North and Midwest. In the South, 53% of businesses generate less than $500,000 in annual revenue, while 59% have fewer than five employees. Only 36% have been operating for more than 10 years, compared with 43% in the Midwest. Those characteristics can influence how businesses interact with credit. A younger business, for example, may have had less time to establish multiple commercial credit relationships. That pattern appears in Experian’s data. Across the United States, the average number of commercial credit accounts per business has declined from approximately 1.8 in 2018 to 1.5 in 2026. The South experienced the steepest decline and currently has the fewest accounts per business. At the same time, commercial credit inquiries have increased since 2023, most recently peaking in early 2026. Inquiry rates have typically been higher in the Midwest and South. The combination of fewer existing accounts and elevated inquiry activity provides useful context for lenders seeking to understand the credit needs of a growing population of younger businesses. Credit utilization tells another part of the story Regional differences also appear after businesses establish credit relationships. Businesses in the Midwest and North opening new commercial accounts tend to receive higher lines than businesses in the South and West. At the same time, businesses in the South show higher commercial card utilization despite carrying somewhat lower average balances. Experian’s analysis points to lower credit lines as an important factor behind that relationship. These trends reinforce why looking beyond a single credit metric can be important. Higher utilization, for example, can take on additional context when considered alongside credit-line size, business age, balances and regional business formation. Growth brings opportunities—and risk factors to monitor Despite significant growth and changes in business composition, regional credit performance has remained relatively steady. Commercial delinquencies across all regions are near pre-pandemic levels, while commercial credit risk scores have been relatively stable. There are regional differences worth monitoring, however. Businesses in the South have lower average commercial credit scores than businesses in the other regions analyzed, and delinquency rates tend to be higher in the North and South than in the Midwest and West. The broader takeaway is not simply that there are more small businesses in the South. It is that the composition of the commercial market is evolving alongside that growth. The South represents a growing share of credit-active businesses and new commercial accounts. Many of those businesses are younger, smaller and have fewer established commercial credit relationships. Their credit needs and behaviors may therefore differ from those of more mature businesses in other parts of the country. For commercial lenders and risk leaders, understanding those distinctions can help provide greater context around acquisition, underwriting and portfolio management decisions. As small business formation continues, Experian will continue monitoring where that growth is occurring—and how the changing business landscape is showing up in commercial credit behavior. Learn more ✔ Visit our Commercial Insights Hub for in-depth reports and expert analysis. ✔ Subscribe to our YouTube channel for regular updates on small business trends. ✔ Connect with your Experian account team to explore how data-driven insights can help your business grow. Download the Commercial Pulse Report Visit Commercial Insights Hub Where are small businesses growing in the U.S.? Experian data points to significant growth in the South. While new business formation has increased across the country, the South has consistently recorded the highest volume of new business openings and has seen the number of credit-active businesses grow 70% since 2018—compared with 55% nationally. Where are small businesses growing the most? The South has consistently had the largest volume of new business openings. The South led application growth during 2020–2021, while the West has posted the strongest growth rates since 2022. That distinction is important because it prevents the SEO headline from overstating what the data shows. Why has small business growth been so strong in the southern U.S.? The South has added more than 3.6 million residents since 2020, substantially outpacing other regions. Our report establishes a correlation rather than causation. Related Posts
Explore Experian insights on U.S. manufacturing investment, AI and automation adoption, employment trends, and commercial credit performance.
Experian’s latest Commercial Pulse analysis examines these trends using retail spending data alongside Experian commercial credit data.