Commercial Pulse Highlights | 10.29.2024
Welcome to our October 29th, 2024Commercial Pulse Reportpreview! 📊 In addition to current macroeconomic indicators, in this week’s report we take a closer look at Fintechs and the credit profiles of the businesses that utilize them. Since 2018, the fintech industry has experienced extraordinary growth, fundamentally changing how businesses access and manage financial services. According to our latest Commercial Pulse Report, fintech has grown by over 140% in just a few short years, with the number of fintech companies increasing by 70% between 2019 and 2020 alone. Today, North America dominates the global fintech market, accounting for 34% of its total share.
Watch Our Commercial Pulse Update
Key Takeaways:
- Explosive Growth: The fintech industry has grown by over 140% since 2018, with a 70% increase in the number of fintech companies from 2019 to 2020.
- North American Dominance: North America accounts for over 34% of the global fintech market, making it a key player in the industry’s expansion.
- Innovative Solutions: Fintech companies have transformed traditional financial services with digital solutions in areas like payments, lending, personal finance, and investment management—led by apps like Venmo, Cash App, and Apple Pay.
- Increased Credit Activity: Businesses using fintech financing are 270% more credit-active than those relying on traditional financing, with higher inquiries, trades, credit lines, and balances.
- Higher Risk: Despite increased access to capital, fintech-financed businesses exhibit higher delinquency rates and lower credit scores, presenting added risks for lenders.
Looking for more detailedcommercial insights? Visit ourCommercial Insights Hubfor the latest trends and data on small business performance and credit. Stay informed and ready for what’s ahead!
Related Posts
Learn how lenders can grow small business lending with better credit data, automated decisioning, portfolio analytics, and proactive risk monitoring.
Trucking remains essential to the U.S. economy. According to the Logistics Manager Index, trucks move roughly 72.7% of the nation’s freight by weight. In 2025, they transported 11.26 billion tons of freight and generated $936.4 billion in revenue. Small carriers make up most of the sector: 91.1% operate 10 or fewer trucks. For risk teams, the scale of trucking matters—but so does the gap between strong freight demand and rising pressure on carriers’ finances. Current data show a sector with opportunity, tighter capacity and increasing credit activity, alongside high operating costs and signs of elevated credit risk. The key question is how well individual businesses can turn demand into sustainable cash flow. Watch the Commercial Pulse Update Demand is firm, but industry structure is changing Logistics activity has remained in expansion for nearly three years. In September, transportation capacity was still contracting for a tenth consecutive month, while utilization remained in expansion. The load-to-truck ratio reached its highest point in several years, suggesting that available freight is high relative to available trucks. For carriers that can keep vehicles productive, tight capacity may support pricing and utilization. But those conditions do not automatically translate into stronger margins. Higher rates can be offset by fuel, maintenance, insurance and equipment costs—and those expenses can vary considerably from one business to another. The sector’s structure is shifting, too. Medium- and heavy-duty vehicles in operation were 4.8% higher in the second quarter of 2026 than a year earlier, even as the number of trucking businesses has declined since 2023. Employment has also fallen steadily since 2023, following a post-pandemic surge. Together, these trends point to consolidation and a more complex operating landscape: fleet counts, business counts and employment may tell different parts of the story. Costs are a central source of risk The cost of moving goods continues to climb. In September, the Producer Price Index for truck transportation reached a record high. The Logistics Managers’ Index transportation prices measure rose 2.7 points to 92.7, remaining near historic highs. Diesel prices were roughly 73% above their year-earlier level. For risk leaders, persistent cost pressure matters because it can affect liquidity before it is fully reflected in longer-term performance measures. A carrier may have a full order book and still face working-capital strain if fuel and other operating costs rise faster than it can adjust pricing or collect from customers. This makes it useful to view demand and cost indicators together. A high load-to-truck ratio can be supportive, but it should be read alongside operating expenses, capacity, and the financial flexibility available to each carrier. The sector-wide picture provides context; it cannot establish whether a particular business can absorb the next cost increase. Credit appetite can signal confidence and need Experian commercial credit data show that trucking businesses have generally sought credit more often than businesses in other industries. Commercial inquiries per business have increased over the past two years, and new commercial account openings have trended upward since mid-2024. Average loan amounts have increased over the past year, while average loan sizes across industries have moved closer together since 2024. Credit activity alone does not tell a CRO whether a business is borrowing to support growth or to bridge a cash-flow gap. In a high-cost environment, the same increase in applications can reflect both opportunity and funding need. It is a signal to interpret with other information about the business and its ability to manage obligations. Commercial card patterns add another layer. Trucking businesses tend to open more new commercial card accounts but receive lower credit lines than businesses in many other sectors. Their average balances are lower, yet their utilization is consistently higher. Lower balances can obscure how little unused capacity a business may have. For risk teams, utilization relative to available credit may therefore be more revealing than balance size alone. Watch for deterioration, not just growth Trucking businesses tend to have higher delinquency rates than businesses in other sectors, and average commercial risk scores indicate greater risk. These aggregate patterns deserve attention, especially alongside elevated costs and high card utilization. They do not mean every trucking borrower is deteriorating; they identify areas where portfolio monitoring may be useful. A CRO can use sector trends to sharpen questions at the borrower level: Are operating costs rising faster than revenue? Is available credit shrinking as utilization increases? Are payment patterns changing? Can the business maintain liquidity if freight volumes, pricing or fuel costs shift? The answers will differ across carriers, depending on their operations and financial position. A risk picture with both opportunity and pressure The trucking outlook is constructive but uneven. Strong freight demand and tighter capacity may benefit disciplined carriers. At the same time, record transportation costs, industry consolidation and elevated credit-risk indicators create pressure that may be harder for thinner-margin businesses to absorb. For risk leaders, the most useful takeaway is to avoid treating a strong demand signal as a complete picture of credit health. Pair freight and capacity trends with cost pressure, credit utilization and payment performance, then assess what those patterns mean for each business. In trucking, opportunity is real—but so is the need to understand which carriers have the financial resilience to capture it. Learn more ✔ Visit our Commercial Insights Hub for in-depth reports and expert analysis. ✔ Subscribe to our YouTube channel for regular updates on small business trends. ✔ Connect with your Experian account team to explore how data-driven insights can help your business grow. Download the Commercial Pulse Report Visit Commercial Insights Hub Related Posts
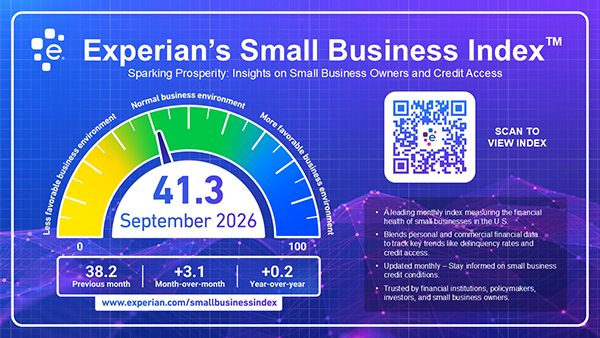
The September index marks the first increase since April 2026 September 2026 Index Value (Sep): 41.3 Previous Month: 38.2 MoM: +3.1 YoY: +0.2 (Sep 2025 = 41.1) The Experian Small Business Index™ increased by 3.1 points to 41.3 in September, which is on par with September of last year. This marks the first increase in the score since April 2026. Small business and business owner risk showed mixed signals in September. Business owners were able to originate more trades and the utilization on their late delinquency trades fell, both positive signs of improving credit risk. They also had more emerging businesses establishing credit than in the previous month. While owners’ consumer trades had higher 31+ day delinquency rates and a higher 61+ day delinquency rate on revolving trades, those values were nearly identical to this time last year. There were signs of increased risk in small business owners’ commercial trades with increases in both commercial trade utilization and 91+ day delinquency rates. On the macroeconomic side, GDP is strong and unemployment continues to be low. The advanced estimate of annualized GDP for the third quarter was 3.4% and unemployment was up slightly from 4.1% in August to 4.2% in September. Inflation continues to be the main challenge in the economy, with headline inflation at 3.7%, up from 3.4% in August, driven largely by energy costs. While fuel prices decreased slightly over the last month, prices for regular and diesel fuel are up 40% and 73%, respectively, from a year ago. These high costs are challenging for both small businesses and small business owners. New businesses continue to form at a very high rate, with nearly 535K new businesses launched in September, well above the historical average. The improvement in the Experian Small Business Index and the improving risk metrics for small business owners’ consumer trades suggest the lending market remains healthy for small businesses. Explore Experian Small Business Index Related Posts