 It’s December, and if you’re like most credit union leaders, your strategic plan is distributed, and the 2020 budget is approved. Before you know it, you and your team will be off and running to pursue the New Year’s goals. Another thing most of us have in common is a strategic membership growth priority. New members are needed to help us take loan and deposit growth to the next level.
Specifically, who are you looking for?
It’s surprising how many credit union leaders have a difficult time clarifying their ideal member(s). They usually come up short after they have called out younger borrowers, active checking account users, prime credit, middle income, homeowners, etc. The reality is in today’s competitive market, these general audiences are not definitive enough. Many then go to market with a limited universe that is too generic to be highly effective.
Savvy marketers have a much deeper understanding of who they are reaching and why. First, they have clearly defined the ideal member i.e. product profitability, relationship profitability, referrals, how they access the credit union, etc. Second, they use data, analytics and demographic segmenting to refine their search further to reveal the ideal member.
They leverage information to understand what drives the potential members decision making. They understand that every potential member does not live the same type of life. They segment markets into groups to understand their shared values and life experiences. These segments include geographic, demographic, financial behavior, and motivation that includes psychographics and social values. Thus, armed with this information, they align the consumer’s needs with the credit union’s products, purpose and strategic goals. This clarity allows them to invest their marketing dollars for the best possible result.
Most credit unions would identify “younger borrowers” as a desired member, so we’ve laid out two examples of just how different this member can look.
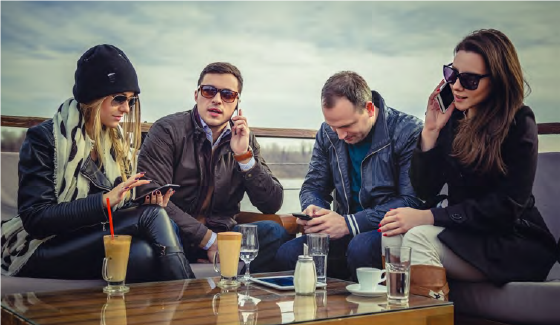
Ambitious Singles – is a demographic segment comprised of younger cutting-edge singles living in mid-scale, metro areas that balance work and leisure lifestyles.
- Annual Median income $75k – $100K
- Highly educated
- First time home buyers
- Professionals, upwardly mobile
- Channel preferences for engaging with brands (and their offers) is while watching or streaming TV, listening to their favorite radio apps or while browsing the web on their phones. They are also quite email receptive (but subject lines must be compelling)
Families Matter Most – This segment is comprised of young middle-class families in scenic suburbs, leading family focused lives.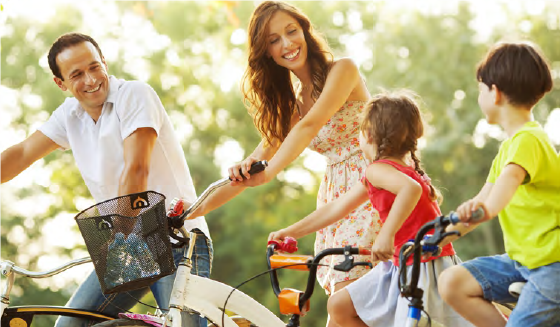
- Annual Median income $75K – $99K
- Have children 4-6 yrs. old
- Educated
- Homeowners
- Child-related purchases
- Credit revolver and auto borrowers (larger vehicles)
- Go online for banking, telecommuting and shopping
Both segments represent younger borrowers with similar incomes, but they have different loan needs, lifestyle priorities and preferences for engaging with a marketing offer. These are just two examples of the segmentation data that is available from Experian.
The segmentation solution provides a framework to help credit unions identify the optimal customer investment strategy for each member segment. This framework helps the credit union optimize their marketing between differentiating segments. For some segments the investment may be directed toward finding the ideal member. Others may be made to find depositors. While many credit unions don’t have infinite marketing budgets or analytical resources, segmentation help marketers more efficiently and effectively pursue the best member or develop member personas to better resonate with existing members. The feedback we have heard from credit union leaders is that the solution is the best segmentation tool they have seen. Learn more about it here.
What your team is up against
Today, credit unions face national competitors that are using state-of-the-art data analytics, first-rate technology and in-depth market segmentation to promote very attractive offers to win new members, deposits, checking accounts and loans. Their offers have a look, feel, message and offer that are relevant to the person receiving the offer. Here are a few recent “offer” examples that we have heard of that should give you pause:
- Fintech companies, like the Lending Club offering auto loan refinances (the offer provides an estimate of refinance interest savings). The ad we saw had an estimated monthly payment of $80.
- PayPal Cashback Mastercard® – with a $300 early use cash bonus and 3% cash back on purchases.
- High limit personal loans that take minutes to apply and to be funded.
- Banks acting alone or in partnership with a fintech to offer online checking accounts with new account opening bonuses ranging from $300-$600.
- and of course, Quicken® Mortgage promoting low rates and fast and seamless origination.
These are just a few recent examples from thousands of offers that are reaching your ideal member. Besides offering great rates, cash back, low fees and seamless service – these offers are guided by robust data analytics and consumer segmentation to reach and engage a well-defined, ideal consumer.
Why it matters
The 2020 race is on. Hopefully your team has clarity of the member(s) they want to reach, access to robust data analytics, in depth consumer insights, reliable credit resources and marketing tools they will need to compete in the toughest financial market any of us have likely ever seen.
If you’re afraid that you can’t afford the right tools when it comes to marketing, consider what the dealer fee is for purchasing an indirect auto loan. What if the 2% or more fee was reallocated to finding organic loan growth with consumers you’re more likely to build a relationship with? Or consider the cost of consistently marketing to the wrong consumer segments with the wrong message, at the wrong time and in the wrong channels. What if you could increase your market engagement rate from 5% to 10%?
Perhaps the best strategic question is can you afford NOT to have the best tools that support future membership growth? If you don’t win your ideal member, somebody else will.
 About Scott Butterfield, CUDE, CCUE
Principal, Your Credit Union Partner
Scott Butterfield is a trusted advisor to the leaders of more than 170 credit unions located throughout the United States. A respected veteran of the CU Movement, he understands the challenges and opportunities facing credit unions today. Scott believes that credit unions matter, and that consumers and small businesses need credit unions to now more than ever.


