Originally published in Adweek
Key takeaways
- 56% of U.S. media buyers plan to increase commerce media spend this year, but 55% cite missing cross-network measurement standards.
- New-to-brand definitions, lookback windows, and attribution rules differ by network, so results across networks can’t be compared directly.
- Off-site commerce media is growing twice as fast as on-site, carrying purchase signal away from the retail environment that created it.
- A shared identity layer lets brands recognize the same consumer across every network, and Experian’s independence from demand-side platforms (DSPs) and supply paths keeps that layer neutral.
Commerce media keeps expanding, and brands are running campaigns across more networks than ever. Most still can’t say which network performed better.
More media networks haven’t produced a more complete view
Investment keeps climbing, and 56% of U.S. media buyers plan to increase commerce media network spending this year, often by reallocating from social, display, and search budgets. Nearly half of advertisers, 47.5%, now fund those campaigns from two or three separate budgets.
Every network in that mix brings its own identity system, audience definitions, and measurement approach. Brands add the fourth or fifth network expecting a fuller picture of performance. Instead, they get more numbers that no one designed to sit next to each other.
I don’t think commerce media has a data problem. Every network has audience data and purchase data. Consistency across them is what nobody has built yet.
The inconsistency lives in the definitions
Take new-to-brand, the metric meant to separate new customers from repeat buyers. It means different things at different networks. Lookback windows differ. Some definitions apply at the brand level, others at the product line. Some count in-store purchases, others count only digital. View-through credit varies across display, video, and connected TV (CTV). Attribution windows vary by partner and by format.
Audience portability compounds it. Retailer audiences often can’t move across platforms, so teams rebuild the same strategy in several systems and hope the definitions roughly align.
Over half of advertisers, 55%, name the lack of cross-network measurement standards as a top challenge. A campaign can look stronger on one network than another for no reason other than a different reporting rule. You can’t move budget on numbers that don’t compare or show incremental lift, and yet most teams are trying to.
Off-site growth makes this harder to ignore
On-site inventory is approaching its ceiling. Sponsored results now appear on 99% of product search pages at Amazon and Walmart, and ad density has reached as high as 50% on key retail search pages. Off-site spending is growing at twice the rate of on-site.
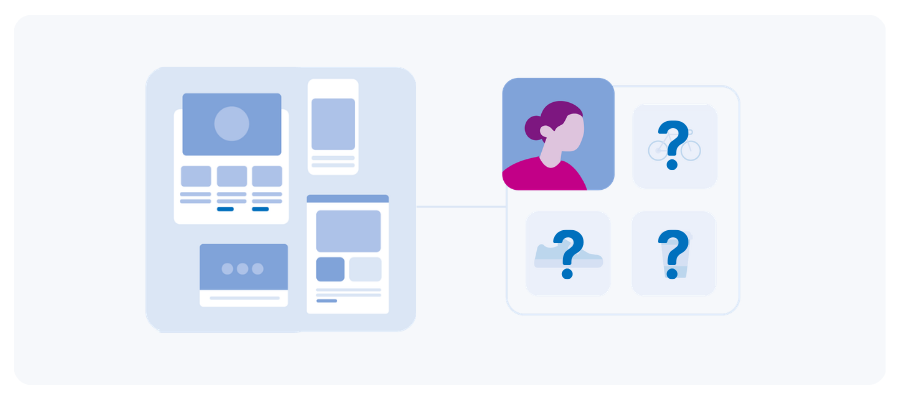
Off-site carries commerce signal away from the environment that created it. Every handoff is a point where the audience definition, the match rate, and the measurement logic have to hold. These are solvable problems, and they show up in the same form at every handoff, which makes them worth solving once instead of campaign by campaign. Fragmentation that stayed manageable inside a retailer’s own properties becomes something to design for the moment the signal travels.
Interoperability starts with a shared identity layer
Brands and networks need a common way to recognize the same consumer wherever a campaign runs. That layer has to draw on retailer, brand, and campaign signals together, and it needs consistent definitions from one network to the next. Get that right and performance sits on common ground, even with every network’s particular reporting rules.
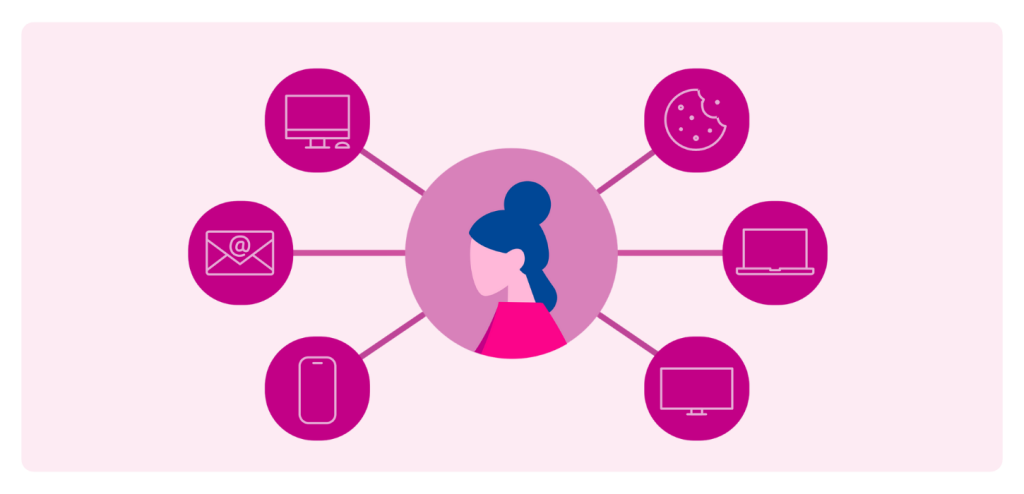
That layer matters more as AI takes over more of the optimization. Models inherit whatever inconsistency sits in the data beneath them, so audience definitions that shift from one network to the next degrade every decision that follows. Better models won’t fix a fragmented identity layer, but they will scale its errors faster. Networks can get ahead of this by settling the identity layer first, standardizing audience definitions so they hold on-site and off-site and give the models downstream something dependable to learn from.
Signal expansion belongs in the same conversation. First-party data reflects the customers who logged in, joined the loyalty program, or completed a transaction. Irregular buyers, emerging segments, and high-value prospects who are actively in-market show up faintly or not at all in that view, even though signal about them exists elsewhere in the ecosystem. A shared identity layer that connects to a marketplace of data providers closes part of that gap, and it does so without asking any network to hand over raw records.
This is also what opens commerce media to brands that will never own a media network. Most companies sitting on valuable first-party data don’t have the traffic or the assortment to build what Amazon and Walmart built, and they don’t need to. Combining signal with trusted partners produces audiences larger and more valuable than any one of those brands holds alone. That’s how a brand participates in commerce media without becoming a media company.
Networks need infrastructure, and neutrality decides whose
A mid-sized commerce media network runs into the same ceiling from the other direction. Owned inventory has a limit, and so does owned data. Growing past both means off-site reach, enriched audiences, and measurement that holds up next to the largest players, and building all of that in-house isn’t realistic for most networks. What they need is infrastructure that supports expansion without giving up control of the customer relationship.
That makes the choice of whose infrastructure a consequential one. Brands and networks should look hard at the commercial position of any partner they put at the center of identity and measurement. A partner with interests in a specific demand-side platform (DSP), supply path, or set of agency relationships gains visibility into every deal that moves through it, and that visibility shapes incentives over time. Networks are right to weigh it carefully.
Experian competes in none of those layers. Our position strengthens when the ecosystem stays open and brands keep the freedom to work across partners, platforms, and evolving technologies. Independence is what makes shared infrastructure possible.
Consistency is the constraint on the next round of growth
Commerce media maturity trails its ambition. 42% of teams believe they have operationalized commerce media, while only 13% qualify as advanced against leadership, technology, measurement, and operations.
Closing that gap depends on identity discipline more than network count. A brand that recognizes the same consumer across every network it buys can compare results, move budget with confidence, and hold every partner to one standard. Without that, each new network adds spend and subtracts clarity.
Consistency is what turns commerce media from a set of separate programs into something a brand can actually manage.
About the author
Kevin Dunn
Chief Revenue Officer, Experian
Kevin Dunn joins Experian Marketing Services with more than 20 years of leadership experience across marketing and advertising technology, most recently serving as Senior Vice President of Brands and Agencies at LiveRamp. In that role, he led growth across retail, CPG, travel, hospitality, financial services, and healthcare, overseeing new business, account expansion, and channel partnerships.
Kevin is known for building cohesive, accountable teams and leading with optimism, clarity, and a strong sense of shared purpose. His leadership philosophy centers on empowering people, driving positive outcomes for clients and fostering a culture where teams can grow, take smart risks, and succeed together.
Latest posts
NEW YORK, Nov. 29, 2016 /PRNewswire/ — For the second consecutive year, Tapad, part of Experian, has been listed among Deloitte’s Technology Fast 500™, a ranking of the 500 fastest-growing technology, media, telecommunications, life sciences and energy tech companies in North America. Tapad, number 147 on the 2016 Deloitte list, is the leading provider of unified, cross-device marketing technology solutions. “It is an honor to once again be recognized by Deloitte for our growth and momentum, particularly given the stature of the other technology companies on the list,” said Are Traasdahl, founder and CEO of Tapad. “Our product innovation, particularly in TV analytics and measurement, is a major contributor to our progress. I’m extremely proud of our hard-working, talented team for continually executing at such a high level.” “Today, when every organization can be a tech company, the most effective businesses not only foster the courage to explore change, but also encourage creativity in using and applying existing assets in new ways, as resourcefully as possible,” said Sandra Shirai, principal, Deloitte Consulting LLP and U.S. technology, media and telecommunications industry leader. “This ingenious approach to innovation calls for the encouragement of curiosity and collaboration both within and outside the office walls.” “This year’s Fast 500 winners showcase that when organizations are open to diverse perspectives and insights, they are able to create an environment for their employees and customers to see the possibilities and ingenious solutions that might lie ahead,” added Jim Atwell, national managing partner of the emerging growth company practice, Deloitte & Touche LLP. “Entrepreneurial environments foster change and innovation within businesses, and we look forward to watching these companies continue to drive change across all sectors.” Contact us today
Distribution via LiveRamp enables seamless cross-device customer experiences through more platforms NEW YORK, Nov. 15, 2016 /PRNewswire/ — Tapad, now part of Experian and the leading provider of unified cross-device marketing technology solutions, today announced an expanded partnership with LiveRamp™, an Acxiom® company and leading provider of omnichannel identity resolution, to make the proprietary Tapad Device Graph™ accessible beyond Tapad-hosted direct integrations. Through LiveRamp, Tapad’s Device Graph Access now extends to more than 400 ad tech and mar tech platforms. Tapad’s Device Graph™ enables marketers to understand, monetize and measure consumer engagement across all digital channels, and Tapad’s unified consumer view is recognized as one of the most accurate, scalable cross-device solutions in the market today. Through the expanded partnership with LiveRamp, the Tapad Device Graph can be distributed to the hundreds of platforms used to reach consumers on digital channels and measure campaign performance – even as devices are added daily to Tapad’s extensive graph. “Increasingly, marketers want access to cross-device targeting and measurement capabilities within their preferred platforms,” said Anneka Gupta, chief product officer of LiveRamp. “Our expanded partnership makes it easy for marketers to access Tapad’s graph through the rapidly growing set of integrations available in our partner ecosystem.” This is the latest of several initiatives between the two technology platforms designed to make the integration of cross-screen platforms seamless, privacy-safe and easy to use for dynamic and engaging marketing efforts. “During the past year, Tapad has expanded its global presence and rapidly grown its data business – Tapad Coral – doubling the number of companies integrating our device graph into their platforms and growing our annualized run rate by 210%,” said Pierre Martensson, GM of Tapad Coral and APAC. “Our expanded partnership with LiveRamp positions us to meet the increased demand for Tapad Device Graph Access and enable new platforms to apply our graph with unprecedented speed.” Contact us today
Cross-Screen Pioneer Explores the Power of Connected Cars as a Vehicle for Customer Engagement LAS VEGAS, NV — (October 26, 2016) –Kate O’Loughlin, GM of Media for Tapad, addressed the J.D. Power Automotive conference audience today in Las Vegas, NV. With more than 1,400 participants representing every facet of the automotive marketing profession, the conference has become the industry’s leading marketing event. Bringing the unified, cross-screen perspective to the stage, O’Loughlin discussed the vital role of connected cars in the consumer engagement process. She is a founding member of Tapad which launched the world’s first cross-screen marketing technology in 2010. Tapad was acquired by the Telenor Group early in 2016. Key points from O’Loughlin’s J.D. Power 2016 address included: The marketers who deliver relevant and engaging content in a privacy-safe setting will be in the strongest position to navigate the proliferation of connected devices, including the connected points in cars. As automakers innovate the technology in cars, marketers need to be prepared for the size and diversity of data available for understanding consumers. It’s going to be increasingly difficult to wade through the data, so now is the time to build a solid framework for understanding the person behind the data. Marketers who evolve — and take a holistic approach — to their campaign measurements will achieve marked improvements in efficiency and an enhanced understanding of their core audiences. Actionable brand engagement metrics like Viewable Exposure Time (VET) will continue to overtake traditional advertising performance metrics. VET evaluates the optimal amount of time an ad is present on a screen to incite consumer action. In early testing by Tapad, campaigns that employ VET see conversion rate performance improvements from 13 to 60%. The consumer-centric technology solutions of the future need to be as scalable as they are affordable. Learn more about Tapads’ recommended Viewable Exposure Time metric contact us today! Contact us today