Originally published in Adweek
Key takeaways
- 56% of U.S. media buyers plan to increase commerce media spend this year, but 55% cite missing cross-network measurement standards.
- New-to-brand definitions, lookback windows, and attribution rules differ by network, so results across networks can’t be compared directly.
- Off-site commerce media is growing twice as fast as on-site, carrying purchase signal away from the retail environment that created it.
- A shared identity layer lets brands recognize the same consumer across every network, and Experian’s independence from demand-side platforms (DSPs) and supply paths keeps that layer neutral.
Commerce media keeps expanding, and brands are running campaigns across more networks than ever. Most still can’t say which network performed better.
More media networks haven’t produced a more complete view
Investment keeps climbing, and 56% of U.S. media buyers plan to increase commerce media network spending this year, often by reallocating from social, display, and search budgets. Nearly half of advertisers, 47.5%, now fund those campaigns from two or three separate budgets.
Every network in that mix brings its own identity system, audience definitions, and measurement approach. Brands add the fourth or fifth network expecting a fuller picture of performance. Instead, they get more numbers that no one designed to sit next to each other.
I don’t think commerce media has a data problem. Every network has audience data and purchase data. Consistency across them is what nobody has built yet.
The inconsistency lives in the definitions
Take new-to-brand, the metric meant to separate new customers from repeat buyers. It means different things at different networks. Lookback windows differ. Some definitions apply at the brand level, others at the product line. Some count in-store purchases, others count only digital. View-through credit varies across display, video, and connected TV (CTV). Attribution windows vary by partner and by format.
Audience portability compounds it. Retailer audiences often can’t move across platforms, so teams rebuild the same strategy in several systems and hope the definitions roughly align.
Over half of advertisers, 55%, name the lack of cross-network measurement standards as a top challenge. A campaign can look stronger on one network than another for no reason other than a different reporting rule. You can’t move budget on numbers that don’t compare or show incremental lift, and yet most teams are trying to.
Off-site growth makes this harder to ignore
On-site inventory is approaching its ceiling. Sponsored results now appear on 99% of product search pages at Amazon and Walmart, and ad density has reached as high as 50% on key retail search pages. Off-site spending is growing at twice the rate of on-site.
Off-site carries commerce signal away from the environment that created it. Every handoff is a point where the audience definition, the match rate, and the measurement logic have to hold. These are solvable problems, and they show up in the same form at every handoff, which makes them worth solving once instead of campaign by campaign. Fragmentation that stayed manageable inside a retailer’s own properties becomes something to design for the moment the signal travels.
Interoperability starts with a shared identity layer
Brands and networks need a common way to recognize the same consumer wherever a campaign runs. That layer has to draw on retailer, brand, and campaign signals together, and it needs consistent definitions from one network to the next. Get that right and performance sits on common ground, even with every network’s particular reporting rules.
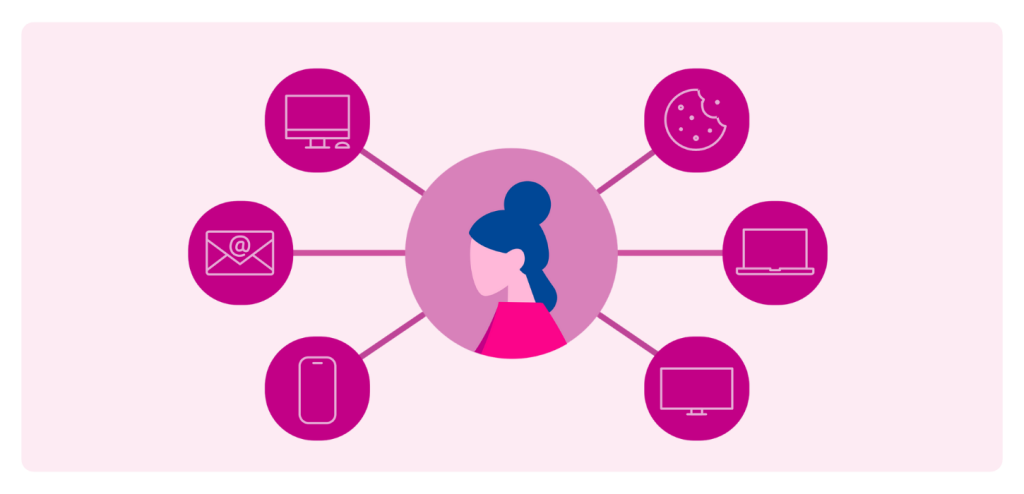
That layer matters more as AI takes over more of the optimization. Models inherit whatever inconsistency sits in the data beneath them, so audience definitions that shift from one network to the next degrade every decision that follows. Better models won’t fix a fragmented identity layer, but they will scale its errors faster. Networks can get ahead of this by settling the identity layer first, standardizing audience definitions so they hold on-site and off-site and give the models downstream something dependable to learn from.
Signal expansion belongs in the same conversation. First-party data reflects the customers who logged in, joined the loyalty program, or completed a transaction. Irregular buyers, emerging segments, and high-value prospects who are actively in-market show up faintly or not at all in that view, even though signal about them exists elsewhere in the ecosystem. A shared identity layer that connects to a marketplace of data providers closes part of that gap, and it does so without asking any network to hand over raw records.
This is also what opens commerce media to brands that will never own a media network. Most companies sitting on valuable first-party data don’t have the traffic or the assortment to build what Amazon and Walmart built, and they don’t need to. Combining signal with trusted partners produces audiences larger and more valuable than any one of those brands holds alone. That’s how a brand participates in commerce media without becoming a media company.
Networks need infrastructure, and neutrality decides whose
A mid-sized commerce media network runs into the same ceiling from the other direction. Owned inventory has a limit, and so does owned data. Growing past both means off-site reach, enriched audiences, and measurement that holds up next to the largest players, and building all of that in-house isn’t realistic for most networks. What they need is infrastructure that supports expansion without giving up control of the customer relationship.
That makes the choice of whose infrastructure a consequential one. Brands and networks should look hard at the commercial position of any partner they put at the center of identity and measurement. A partner with interests in a specific demand-side platform (DSP), supply path, or set of agency relationships gains visibility into every deal that moves through it, and that visibility shapes incentives over time. Networks are right to weigh it carefully.
Experian competes in none of those layers. Our position strengthens when the ecosystem stays open and brands keep the freedom to work across partners, platforms, and evolving technologies. Independence is what makes shared infrastructure possible.
Consistency is the constraint on the next round of growth
Commerce media maturity trails its ambition. 42% of teams believe they have operationalized commerce media, while only 13% qualify as advanced against leadership, technology, measurement, and operations.
Closing that gap depends on identity discipline more than network count. A brand that recognizes the same consumer across every network it buys can compare results, move budget with confidence, and hold every partner to one standard. Without that, each new network adds spend and subtracts clarity.
Consistency is what turns commerce media from a set of separate programs into something a brand can actually manage.
About the author
Kevin Dunn
Chief Revenue Officer, Experian
Kevin Dunn joins Experian Marketing Services with more than 20 years of leadership experience across marketing and advertising technology, most recently serving as Senior Vice President of Brands and Agencies at LiveRamp. In that role, he led growth across retail, CPG, travel, hospitality, financial services, and healthcare, overseeing new business, account expansion, and channel partnerships.
Kevin is known for building cohesive, accountable teams and leading with optimism, clarity, and a strong sense of shared purpose. His leadership philosophy centers on empowering people, driving positive outcomes for clients and fostering a culture where teams can grow, take smart risks, and succeed together.
Latest posts
Tom Rolph, VP EMEA at Tapad, part of Experian, says that ad-sponsored streaming services can be successful if they can deliver a higher quality viewer experience than other streaming services. Last week, Hulu, the streaming service acquired by Fox and now owned 60 per cent by Disney, announced it will be regularising its ad loads. The streaming service will be bringing ad breaks down to 90 seconds in an effort to deliver a better viewer experience. This is a positive move from Hulu and one which other ad-supported streaming services should follow in order to be successful in a competitive market. Previously ad breaks on Hulu could vary wildly, from 180 seconds to 240 seconds, due to existing deals with its three owners: Disney, Comcast and AT&T. Over in the UK, we haven’t suffered from quite as inconsistent an approach as in the US, but there is still viewer frustration with the ad experience on ITV Hub and All4, where the problem tends to be over exposure of the same ad. Therefore, this move to standardise ad break lengths for streaming platforms is one that should be embraced on both sides of the pond. An important shift in this space will be to limit the number of ads during each show, but have better ad targeting to minimise repetitive advertising and increase the ROI of ad spend. All of which can be accomplished by investing in identity resolution products that can support CTV devices. Last year Ofcom found that in the UK subscriptions to Netflix, Amazon and NOW TV have risen above those to traditional pay TV services. With Netflix and Amazon both ad-free and NOW TV only a limited ad funded model, it’s clear that there is a growing appetite for ad-free viewing models. A fact that is only further supported when you consider the role of the BBC and BBC iPlayer. But the picture isn’t entirely negative for ad-funded models. There is demand for great content on ad-funded services in the UK, with ITV Hub boasting over 1bn requests and 540m hours of TV watched. The ITV Hub mobile app has also been downloaded on over 27m devices across the country – with over 22m people now registered to ITV Hub database, including more than half of Britain’s 16-24 year olds. However, to continue to attract and retain younger viewers, the experience will have to improve. There are several areas where ad-supported streaming providers need to improve in order to remain top players in this space: Ad experienceAs explored above, both volume and repetition of ads can be a turn off for viewers, but with Brits already spending a total of £303.16m every month on TV streaming services, according to Finder.com, there is potential for free, ad-funded models to flourish as people hit a limit on what they are willing to spend. There are already signs of improvement with the ad experience, with ITV just signing a deal with Amobee to allow for addressable ads on ITV Hub, while Sky’s AdSmart technology remains best in class and has now crossed over the pond to be used by Comcast stablemate NBC. Server reliabilityA cursory search finds little evidence of ongoing reliability problems with Netflix, but much evidence of problems with ITV Hub and All4, which are both prone to crashing. To compete with bigger players with massive server farms, server capacity needs to be tackled. This is especially true when it comes to live events, where many people will recall ITV Hub’s famous fails during the World Cup. While even some of the larger players have had similar streaming issues (for example, Amazon’s move into live sports streaming when they had to pull UK streaming of the US Open Tennis due to user complaints), viewing experience should be prioritised as the space gets increasingly competitive. Getting the content rightAmazon and Netflix have huge content budgets, but UK broadcasters remain strong in this regard, Channel 4 has enjoyed viewing figures of 7.5m for the Great British Bake Off, while ITV pulled in 13.7m for I’m A Celebrity. By building on UK-specific content that speaks to UK audiences, ad-supported streaming services can continue to pull in more viewers. Mobile accessMore and more Brits are choosing to watch TV content on their smartphone or tablet, according to UKOM-approved comScore data. In fact, 6.5m adults visited the BBC iPlayer app to watch video on either a smartphone or tablet, edging out Netflix which attracted 5.8m Getting the experience right on mobile, with the option to download content so it can be viewed in areas of low or no signal, is key.If UK ad-supported TV stations can crack these key areas for their Connected TV offering then they will be set up to succeed and offer a true home-grown alternative to the US streaming giants. Full article here. Contact us today
Tapad’s, part of Experian, SVP of Identity shows us how marketers might communicate seamlessly through emerging channels like voice, the smart home, and, yes, podcasts.In his relatively new role as senior vice president of identity at Tapad, a part of Experian, Ajit Thupil keeps a close eye on the evolution of marketing as it becomes more intent on using data and identity technology to track ROI. Here he sits with Chris Wood at Tapad’s New York offices to discuss the future of identity. (To capture the inventive atmosphere at this location, the room they chatted in was named after Leonardo da Vinci.) For Thupil, it all comes back to the customer, whether it’s a brand client or a consumer. Brands want measurability and customers demand a seamless experience across the many devices they use in a day. While consumers are understandably reticent about giving up personally identifiable information (PII), current identity solutions use anonymous data profiles to connect the dots at the individual or household level. Given the frequency that users switch devices, along with their tendency to share bigger screens like TVs, there’s no dearth of challenges for this “head of problem solving” to solve. Contact us today
Joint solution will enhance accuracy and reach across North America, EMEA and APAC NEW YORK, April 17, 2019 /PRNewswire/ — Tapad, a global marketing technology company and leader in digital identity resolution solutions, today announced a new joint capability with Arm®Treasure DataTM , a leader in enterprise customer data management. The partnership combines The Tapad GraphTM technology with Arm Treasure Data’s robust enterprise Customer Data Platform (CDP), enabling advertisers in the Arm Treasure Data marketplace to access Tapad’s datasets. With the integration of Tapad’s Graph and Arm Treasure Data’s existing first party data, marketers will be able to deliver scalable, cross-device messaging with precision. In addition, marketers can benefit from anonymous customer journey analysis, audience expansion and online and offline attribution. Arm Treasure Data’s APAC market customers will have access to expanded audience reach by leveraging Tapad’s global, proprietary datasets. While Tapad will be able to extend its presence into the APAC region, tapping into Arm Treasure Data’s existing footprint. “The Tapad GraphTM is a trusted and established platform with a history of innovation,” said Stephen Lee, Senior Director, Business Development, Arm Treasure Data. “Integrating Tapad’s technology into the Arm Treasure Data CDP will allow for streamlined experiences across markets, achieving global scalable reach.” For more information about The Tapad GraphTM, or to request a demo, visit our identity page. About Tapad Tapad, Inc. is a global marketing technology company and leader in digital identity resolution solutions. The Tapad GraphTM, and related solutions, provide a privacy-safe approach to connecting device identifiers to brand and marketer data, thereby allowing for enhanced measurement, attribution, reach and ROI of marketing campaigns. The Tapad GraphTM enables marketers around the world to maximize campaign effectiveness and drive business results. Tapad is recognized across the industry for its innovation, growth and workplace culture, and has earned numerous awards, including the TMCnet Tech Culture Award. Based in New York, Tapad also has offices in Chicago, London, Oslo, Singapore and Tokyo, and is a wholly owned subsidiary of Telenor Group. About Treasure Data Arm Treasure Data enterprise Customer Data Platform (CDP) unifies data from multiple sources – online, offline, IoT and device generated data – and empowers enterprises to disrupt their markets with superior customer experiences. Our customers are creating transformational customer relationships by connecting the data dots with our CDP. Arm Treasure Data is fully owned by Arm Holdings and has a global customer base of over 300 enterprises including Fortune 500 and Global 2000 companies. Our clients manage over 130 trillion records, resulting in more predictable and profitable business results. Contact us today