Originally published in Adweek
Key takeaways
- 56% of U.S. media buyers plan to increase commerce media spend this year, but 55% cite missing cross-network measurement standards.
- New-to-brand definitions, lookback windows, and attribution rules differ by network, so results across networks can’t be compared directly.
- Off-site commerce media is growing twice as fast as on-site, carrying purchase signal away from the retail environment that created it.
- A shared identity layer lets brands recognize the same consumer across every network, and Experian’s independence from demand-side platforms (DSPs) and supply paths keeps that layer neutral.
Commerce media keeps expanding, and brands are running campaigns across more networks than ever. Most still can’t say which network performed better.
More media networks haven’t produced a more complete view
Investment keeps climbing, and 56% of U.S. media buyers plan to increase commerce media network spending this year, often by reallocating from social, display, and search budgets. Nearly half of advertisers, 47.5%, now fund those campaigns from two or three separate budgets.
Every network in that mix brings its own identity system, audience definitions, and measurement approach. Brands add the fourth or fifth network expecting a fuller picture of performance. Instead, they get more numbers that no one designed to sit next to each other.
I don’t think commerce media has a data problem. Every network has audience data and purchase data. Consistency across them is what nobody has built yet.
The inconsistency lives in the definitions
Take new-to-brand, the metric meant to separate new customers from repeat buyers. It means different things at different networks. Lookback windows differ. Some definitions apply at the brand level, others at the product line. Some count in-store purchases, others count only digital. View-through credit varies across display, video, and connected TV (CTV). Attribution windows vary by partner and by format.
Audience portability compounds it. Retailer audiences often can’t move across platforms, so teams rebuild the same strategy in several systems and hope the definitions roughly align.
Over half of advertisers, 55%, name the lack of cross-network measurement standards as a top challenge. A campaign can look stronger on one network than another for no reason other than a different reporting rule. You can’t move budget on numbers that don’t compare or show incremental lift, and yet most teams are trying to.
Off-site growth makes this harder to ignore
On-site inventory is approaching its ceiling. Sponsored results now appear on 99% of product search pages at Amazon and Walmart, and ad density has reached as high as 50% on key retail search pages. Off-site spending is growing at twice the rate of on-site.
Off-site carries commerce signal away from the environment that created it. Every handoff is a point where the audience definition, the match rate, and the measurement logic have to hold. These are solvable problems, and they show up in the same form at every handoff, which makes them worth solving once instead of campaign by campaign. Fragmentation that stayed manageable inside a retailer’s own properties becomes something to design for the moment the signal travels.
Interoperability starts with a shared identity layer
Brands and networks need a common way to recognize the same consumer wherever a campaign runs. That layer has to draw on retailer, brand, and campaign signals together, and it needs consistent definitions from one network to the next. Get that right and performance sits on common ground, even with every network’s particular reporting rules.
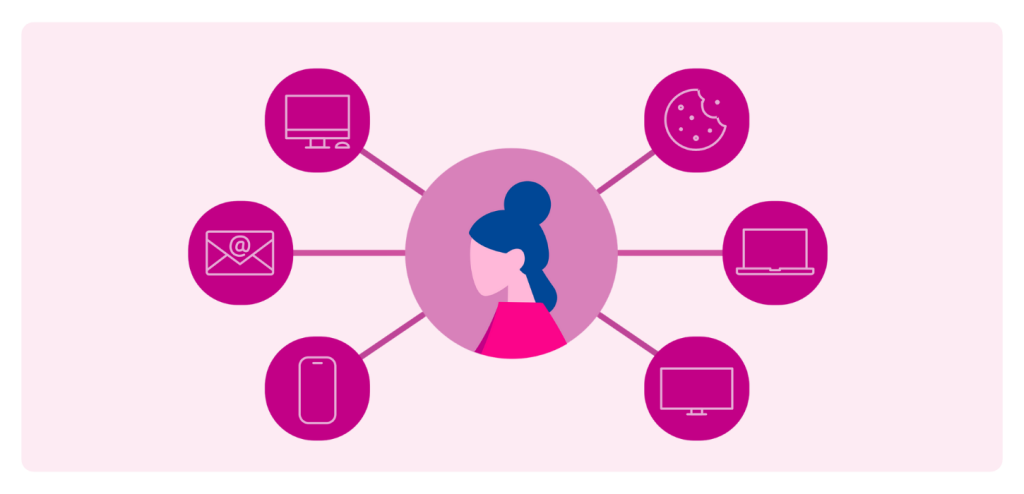
That layer matters more as AI takes over more of the optimization. Models inherit whatever inconsistency sits in the data beneath them, so audience definitions that shift from one network to the next degrade every decision that follows. Better models won’t fix a fragmented identity layer, but they will scale its errors faster. Networks can get ahead of this by settling the identity layer first, standardizing audience definitions so they hold on-site and off-site and give the models downstream something dependable to learn from.
Signal expansion belongs in the same conversation. First-party data reflects the customers who logged in, joined the loyalty program, or completed a transaction. Irregular buyers, emerging segments, and high-value prospects who are actively in-market show up faintly or not at all in that view, even though signal about them exists elsewhere in the ecosystem. A shared identity layer that connects to a marketplace of data providers closes part of that gap, and it does so without asking any network to hand over raw records.
This is also what opens commerce media to brands that will never own a media network. Most companies sitting on valuable first-party data don’t have the traffic or the assortment to build what Amazon and Walmart built, and they don’t need to. Combining signal with trusted partners produces audiences larger and more valuable than any one of those brands holds alone. That’s how a brand participates in commerce media without becoming a media company.
Networks need infrastructure, and neutrality decides whose
A mid-sized commerce media network runs into the same ceiling from the other direction. Owned inventory has a limit, and so does owned data. Growing past both means off-site reach, enriched audiences, and measurement that holds up next to the largest players, and building all of that in-house isn’t realistic for most networks. What they need is infrastructure that supports expansion without giving up control of the customer relationship.
That makes the choice of whose infrastructure a consequential one. Brands and networks should look hard at the commercial position of any partner they put at the center of identity and measurement. A partner with interests in a specific demand-side platform (DSP), supply path, or set of agency relationships gains visibility into every deal that moves through it, and that visibility shapes incentives over time. Networks are right to weigh it carefully.
Experian competes in none of those layers. Our position strengthens when the ecosystem stays open and brands keep the freedom to work across partners, platforms, and evolving technologies. Independence is what makes shared infrastructure possible.
Consistency is the constraint on the next round of growth
Commerce media maturity trails its ambition. 42% of teams believe they have operationalized commerce media, while only 13% qualify as advanced against leadership, technology, measurement, and operations.
Closing that gap depends on identity discipline more than network count. A brand that recognizes the same consumer across every network it buys can compare results, move budget with confidence, and hold every partner to one standard. Without that, each new network adds spend and subtracts clarity.
Consistency is what turns commerce media from a set of separate programs into something a brand can actually manage.
About the author
Kevin Dunn
Chief Revenue Officer, Experian
Kevin Dunn joins Experian Marketing Services with more than 20 years of leadership experience across marketing and advertising technology, most recently serving as Senior Vice President of Brands and Agencies at LiveRamp. In that role, he led growth across retail, CPG, travel, hospitality, financial services, and healthcare, overseeing new business, account expansion, and channel partnerships.
Kevin is known for building cohesive, accountable teams and leading with optimism, clarity, and a strong sense of shared purpose. His leadership philosophy centers on empowering people, driving positive outcomes for clients and fostering a culture where teams can grow, take smart risks, and succeed together.
Latest posts
Every year, the Experian team attends the Consumer Electronics Show (CES) in Las Vegas, to immerse ourselves in the world’s most significant consumer tech showcase and stay at the forefront of the latest technological advancements and innovations that shape the AdTech industry. This year’s event was a vibrant melting pot of innovation and vision, from streamers taking a bigger bite of the advertising pie to the emergence of AI-powered solutions and drone delivery services. Amidst these advancements, the dynamic interplay of technology, media, and advertising raised important questions, especially in the context of evolving regulations and cookie deprecation. During CES, we captured insights from various thought leaders, and in the coming months, we’ll be sharing these valuable perspectives with you. Watch the video below for full insights coming from our content studio onsite during the event. Or, keep reading for a recap on four key trends from CES and what they mean for your business in 2024! “My first CES was a major success. You could feel the buzz in the air as new ideas and partnerships were being created within and across industries. The intersection of the different players within retail media, connected TV, retail technology, the demand and supply-side, and agencies all in an ever-changing world of regulation and privacy begs for a solution that can maximize a successful outcome for all.”anne passon, sr director, sales, retail & cpg 1. Audience targeting: How first- and third-party data work together A central theme at CES was the importance of audience targeting, highlighting the crucial role of first-party data. However, it’s clear that to maximize its potential, this data needs to be augmented with sophisticated identity solutions and enriched with third-party insights, all while navigating the complexities of privacy regulations. This integrated approach is vital to understanding audiences and for creating more effective marketing strategies that comply with privacy regulations. 2. Standardizing metrics in retail media networks The challenges around retail media networks, particularly in terms of standardizing metrics like incremental return on ad spend (iROAS), were a hot topic at CES. This complexity around this topic underscores the need for neutral, expert third parties to help bring clarity and consensus, aiding businesses in navigating this multifaceted domain. 3. The challenge of switching data solutions Discussions covered the broader challenges associated with transitioning to new data solutions. For businesses, this involves a critical assessment of the benefits versus the costs and complexities of adopting new platforms or systems. This decision-making process is increasingly significant as data strategies become integral to marketing success. 4. Identity solutions in a cookieless future With the industry moving toward a cookieless future, the spotlight at CES was on the importance of robust identity solutions. Understanding the functionality and necessity of various universal IDs is essential to minimize data loss and maintain effective targeting. Investing in flexible and adaptable identity solutions like the Experian Graph is essential to maintain effective targeting and audience engagement in this new landscape. Announcements and advertising innovations at CES 2024 CES was a stage for significant announcements and innovative marketing initiatives: Criteo and Albertsons announced their collaboration in retail media. Instacart’s partnership with Google for enhanced shopping ads and AI shopping carts. NBCUniversal’s advancements in streamlining programmatic advertising. Brands like Netflix, LG, Freewheel, and Amazon Ads also captured attention with their creative marketing strategies, ranging from unique collaborations to themed promotions and captivating events. These insights from CES provide a glimpse into the future of technology, media, and advertising. They highlight the need for adaptability, innovation, and informed decision-making in these dynamic industries, especially in the context of privacy regulations. Stay tuned for our series of posts where we’ll dive deeper into these topics, sharing exclusive insights from industry thought leaders. Follow us on LinkedIn or sign up for our email newsletter for more informative content on the latest industry insights and data-driven marketing. Contact us Latest posts
Short-form video content is becoming more prevalent on video-sharing platforms. Keep up with trends and marketing strategies to stay relevant.
Since joining the Truthset Data Collective in 2023, Experian has consistently demonstrated leadership in data accuracy. The latest Q2 2025 analysis reaffirms this commitment.