Experian Commercial Pulse Report | 3/11/2025
After 26 months of decline, American manufacturing is making a comeback—led by the smallest players in the game. Small businesses are redefining an entire sector.
Watch Our Commercial Pulse Update
Green Shoots of Growth Seen in America’s Small Manufacturers
The U.S. manufacturing sector has been in a period of contraction for more than two years, but recent data suggests that a turning point may be on the horizon. The Purchasing Managers’ Index (PMI) reached 50.9 in January, breaking past the critical 50-point threshold for the first time in 26 months. This indicates that manufacturing activity is shifting from contraction to expansion, a positive sign for small businesses that have been a major driver of growth in the sector.
Over the past five years, the number of manufacturing businesses in the U.S. has grown by 13 percent, with small businesses leading the charge. Many of these businesses operate with fewer than nine employees and generate under $1 million in revenue, yet they now account for over 70 percent of commercial credit activity in the manufacturing sector.
This shift represents a significant change in an industry historically dominated by large, long-established firms. Small manufacturers are proving to be agile, innovative, and capable of carving out new opportunities in a challenging economic landscape.
Access to Credit is Key to Growth
One of the most striking trends in the sector is the increasing reliance on commercial credit cards. Since 2010, commercial card usage in manufacturing has surged by 37 percent. This suggests that small manufacturers are turning to flexible credit solutions to manage cash flow, finance equipment, and fund operational expenses.
Unlike traditional bank loans, commercial credit cards offer businesses quick access to funding with fewer restrictions, making them an attractive option for small manufacturers looking to scale operations. The consistent availability of credit will be a crucial factor in determining whether these businesses can sustain growth in the coming months.
What’s Driving the Manufacturing Sector’s Rebound?
Several factors contribute to the potential comeback of U.S. manufacturing, including:
- Stabilizing Consumer Demand – Although consumer confidence declined in February, retail sales have remained steady. With personal income rising, consumer spending could provide support for increased manufacturing output.
- Easing Cost Pressures – Rent inflation has slowed, and mortgage rates have dipped slightly, helping to stabilize business costs.
- Access to Credit Improving – With consumer delinquency rates stabilizing, lenders may loosen credit restrictions, giving small manufacturers greater access to working capital.
Challenges Still Remain
While the manufacturing sector is showing signs of a potential recovery, small businesses still face significant challenges.
- Economic Uncertainty – Inflation remains a concern, rising to 3.0 percent in January, marking the fourth consecutive month of increases.
- Labor Market Pressures – The unemployment rate remains low at 4.1 percent, meaning small manufacturers may struggle to hire skilled workers.
- Rising Interest Rates – While credit availability is improving, higher borrowing costs could limit expansion for some businesses.
Despite these hurdles, the resilience and adaptability of small manufacturers provide a strong foundation for future growth.
What This Means for Small Business Owners
For small manufacturers looking to capitalize on this potential expansion, there are a few key takeaways:
- Monitor Credit Options – As banks and lenders adjust lending policies, it’s essential to stay informed about financing opportunities that can support business growth.
- Invest in Efficiency – With cost pressures stabilizing, now is the time to invest in automation, technology, and process improvements that can boost productivity.
- Stay Agile – The manufacturing sector is cyclical, and market conditions can shift quickly. Flexibility and adaptability will be critical in the months ahead.
The U.S. manufacturing sector is at a crossroads. While uncertainty remains, the recent uptick in PMI, business credit activity, and commercial lending trends suggests that a shift toward expansion is underway. At Experian, we will continue to track these developments and provide insights to help small business owners make informed financial decisions.
To stay ahead of the latest trends:
✔ Visit our Commercial Insights Hub for in-depth reports and expert analysis.
✔ Subscribe to our YouTube channel for regular updates on small business trends.
✔ Connect with your Experian account team to explore how data-driven insights can help your business grow.
Want to learn more? Download the full Commercial Pulse Report for March 11, 2025.
Related Posts
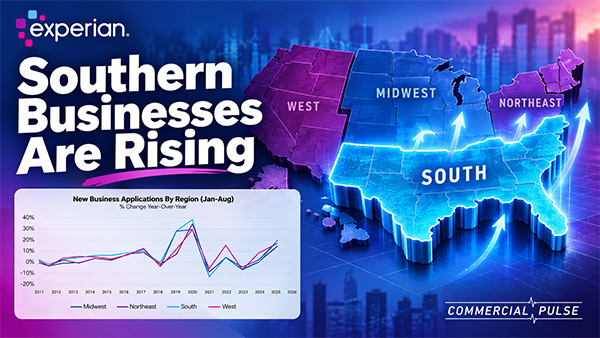
Small business formation remains one of the more notable trends in the U.S. economy. In August 532,000 new businesses launched across the country. While that was down from July, it remained well above historical averages. Since July 2020, an average of 455,000 new businesses have opened each month—56% higher than the pre-pandemic monthly average in 2018 and 2019. But the national numbers only tell part of the story. Watch The Commercial Pulse Update Experian’s latest Commercial Pulse report analysis examines where this growth is occurring and what it means for the commercial credit market. The data show that the South has emerged as an important center of small-business growth. And the businesses driving that expansion tend to have a different profile from their counterparts in other regions. For commercial lenders, understanding those differences can provide valuable context when evaluating new opportunities, credit demand and portfolio risk. Business growth is shifting geographically New business formation has increased across all U.S. regions, but the pace has not been uniform. Prior to 2018, regional differences in growth were relatively modest. During the pandemic years of 2020 and 2021, the South led the country in new business application growth. Since 2022, the West has posted the strongest growth, while the South continues to account for the greatest volume of new business openings. One factor providing context for that growth is population. The population of the South has grown more than 7% since 2019. Since 2020 alone, the region has added more than 3.6 million residents, outpacing every other U.S. region. Meanwhile, populations in other parts of the country declined between 2020 and 2022 before beginning to recover. Business formation and population movement do not necessarily have a simple cause-and-effect relationship. But their parallel growth highlights how the geographic makeup of both consumers and businesses has been changing. Credit-active businesses are growing even faster in the South The shift becomes even clearer when looking at businesses using commercial credit. Experian data shows the number of credit-active businesses in the United States has increased 55% since 2018. Every region participated in that expansion, but the South experienced the greatest growth at 70%, followed by the North at 52%, West at 50% and Midwest at 36%. The South now represents approximately 39% of U.S. credit-active businesses. It also accounted for more than 40% of newly opened commercial accounts in 2026, compared with 37% in 2019. For commercial credit organizations, that means the South represents not just a growing population of businesses, but an increasingly significant share of businesses participating in the commercial credit ecosystem. Southern businesses tend to be smaller and younger The composition of this growth is just as important as its scale. Credit-active businesses in the South and West tend to skew smaller and younger than those in the North and Midwest. In the South, 53% of businesses generate less than $500,000 in annual revenue, while 59% have fewer than five employees. Only 36% have been operating for more than 10 years, compared with 43% in the Midwest. Those characteristics can influence how businesses interact with credit. A younger business, for example, may have had less time to establish multiple commercial credit relationships. That pattern appears in Experian’s data. Across the United States, the average number of commercial credit accounts per business has declined from approximately 1.8 in 2018 to 1.5 in 2026. The South experienced the steepest decline and currently has the fewest accounts per business. At the same time, commercial credit inquiries have increased since 2023, most recently peaking in early 2026. Inquiry rates have typically been higher in the Midwest and South. The combination of fewer existing accounts and elevated inquiry activity provides useful context for lenders seeking to understand the credit needs of a growing population of younger businesses. Credit utilization tells another part of the story Regional differences also appear after businesses establish credit relationships. Businesses in the Midwest and North opening new commercial accounts tend to receive higher lines than businesses in the South and West. At the same time, businesses in the South show higher commercial card utilization despite carrying somewhat lower average balances. Experian’s analysis points to lower credit lines as an important factor behind that relationship. These trends reinforce why looking beyond a single credit metric can be important. Higher utilization, for example, can take on additional context when considered alongside credit-line size, business age, balances and regional business formation. Growth brings opportunities—and risk factors to monitor Despite significant growth and changes in business composition, regional credit performance has remained relatively steady. Commercial delinquencies across all regions are near pre-pandemic levels, while commercial credit risk scores have been relatively stable. There are regional differences worth monitoring, however. Businesses in the South have lower average commercial credit scores than businesses in the other regions analyzed, and delinquency rates tend to be higher in the North and South than in the Midwest and West. The broader takeaway is not simply that there are more small businesses in the South. It is that the composition of the commercial market is evolving alongside that growth. The South represents a growing share of credit-active businesses and new commercial accounts. Many of those businesses are younger, smaller and have fewer established commercial credit relationships. Their credit needs and behaviors may therefore differ from those of more mature businesses in other parts of the country. For commercial lenders and risk leaders, understanding those distinctions can help provide greater context around acquisition, underwriting and portfolio management decisions. As small business formation continues, Experian will continue monitoring where that growth is occurring—and how the changing business landscape is showing up in commercial credit behavior. Learn more ✔ Visit our Commercial Insights Hub for in-depth reports and expert analysis. ✔ Subscribe to our YouTube channel for regular updates on small business trends. ✔ Connect with your Experian account team to explore how data-driven insights can help your business grow. Download the Commercial Pulse Report Visit Commercial Insights Hub Where are small businesses growing in the U.S.? Experian data points to significant growth in the South. While new business formation has increased across the country, the South has consistently recorded the highest volume of new business openings and has seen the number of credit-active businesses grow 70% since 2018—compared with 55% nationally. Where are small businesses growing the most? The South has consistently had the largest volume of new business openings. The South led application growth during 2020–2021, while the West has posted the strongest growth rates since 2022. That distinction is important because it prevents the SEO headline from overstating what the data shows. Why has small business growth been so strong in the southern U.S.? The South has added more than 3.6 million residents since 2020, substantially outpacing other regions. Our report establishes a correlation rather than causation. Related Posts
Explore Experian insights on U.S. manufacturing investment, AI and automation adoption, employment trends, and commercial credit performance.
Experian’s latest Commercial Pulse analysis examines these trends using retail spending data alongside Experian commercial credit data.